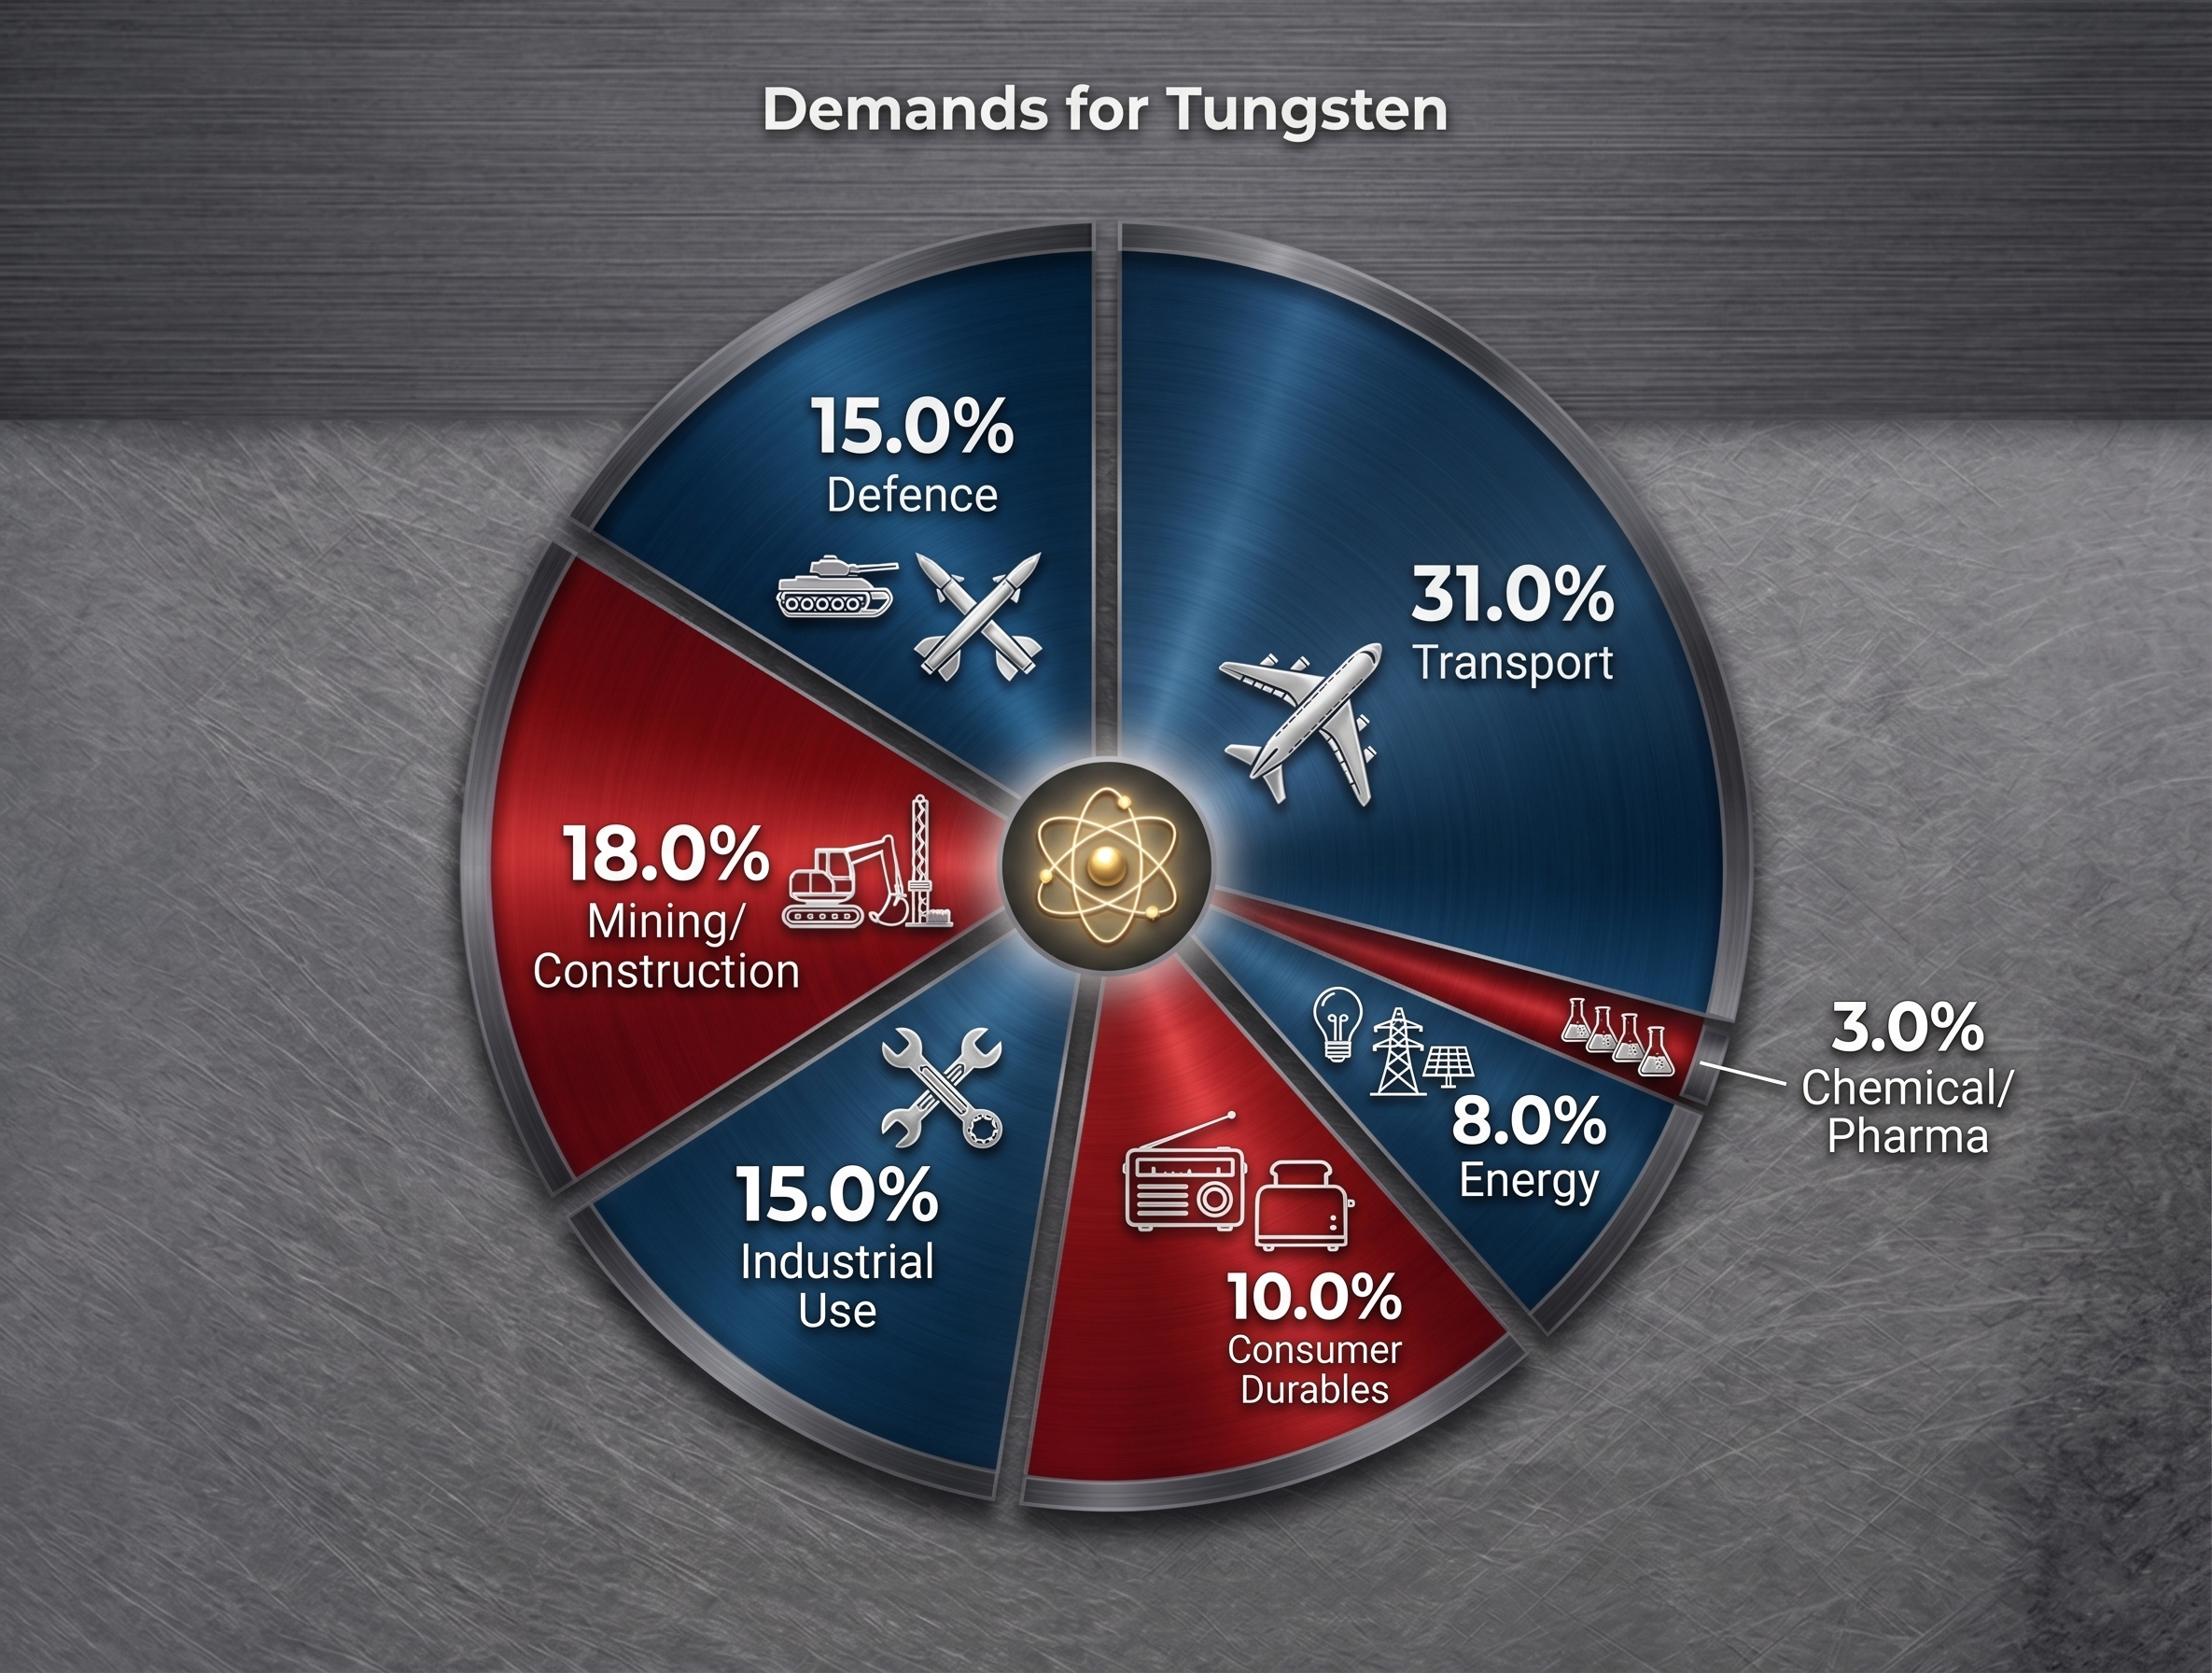
Tungsten is one of the world’s most strategic and supply-constrained minerals. With the highest melting point of any metal and exceptional strength, it is essential for defense systems, aerospace components, semiconductor manufacturing, drilling and mining tools, and electrical and electronic components.
Yet global supply is dominated by China, which accounted for 79% of world mine production in 2025 (USGS Mineral Commodity Summaries 2026) and continues to restrict exports, tightening an already fragile supply chain. Outside of China, production is limited, and few new projects are coming online.
China's own consumption and imports increased significantly in 2025 (USGS), while governments move to secure supply for defense and industry. This widening supply-demand gap has put renewed focus on domestic tungsten sources in North America, especially past-producing districts, where historical production records give explorers a head start.